General Liability Insurance in Georgia
We provide General Liability Insurance solutions to businesses in GA, NC, TN, SC, AL, FL
What Is General Liability Insurance and Who Needs It in Georgia?
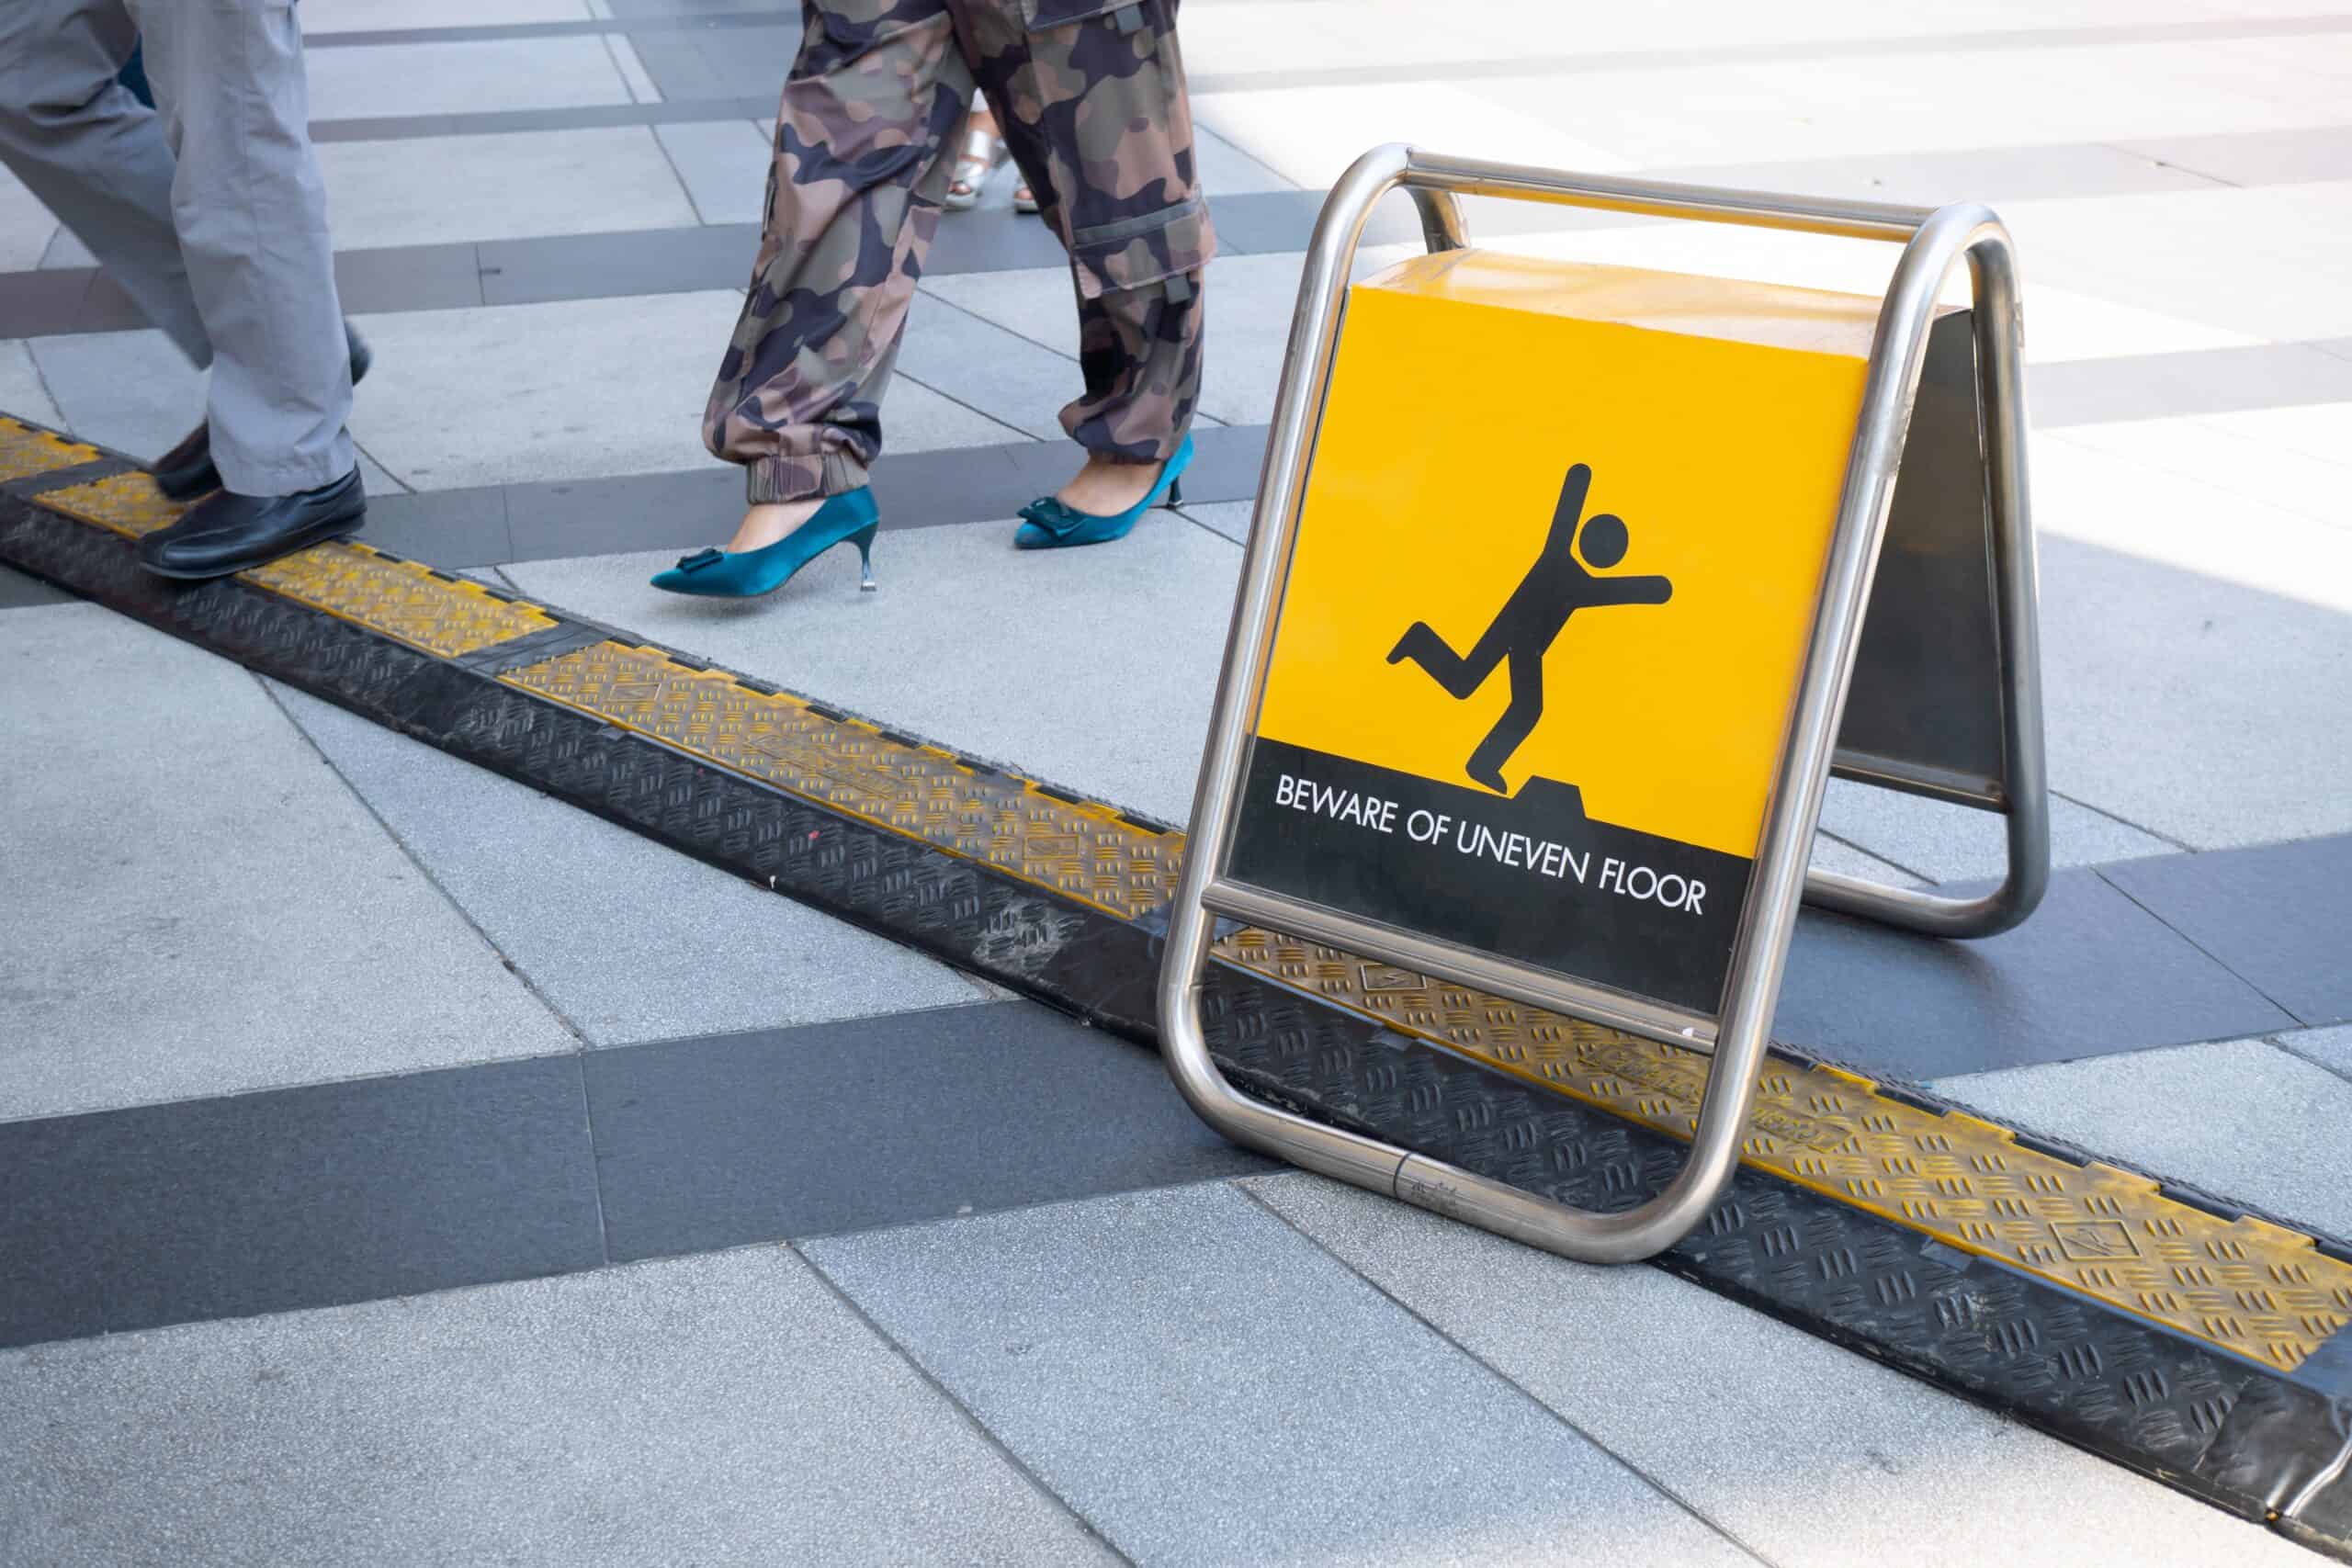
Starting and running a business involves taking calculated risks, but some risks can threaten your company’s survival. General Liability Insurance serves as a fundamental shield for business owners, protecting them from financial ruin due to common third-party claims. This coverage protects your business if a customer, vendor, or passerby suffers bodily injury, property damage, or personal injury like slander on your premises or because of your operations. In Georgia, where commercial activity is thriving, having this protection is not just a safety net; it is often a requirement to secure contracts, lease commercial spaces, or obtain professional licenses.
Who actually needs this? Anyone who interacts with clients face-to-face, accesses client property, or sells physical products needs Business Liability Insurance. For instance, a residential general contractor in Atlanta, a retail shop owner in Savannah, or a consulting firm in Marietta all face daily risks. A single slip-and-fall accident on your property or an accidental scratch on a client’s expensive hardwood floor can lead to costly legal disputes. Without coverage, your business would have to pay out-of-pocket for legal defense fees, medical bills, and any court-ordered settlements, which can easily bankrupt a growing enterprise. Investing in a policy ensures that your daily operations can continue smoothly, even when unexpected accidents happen.
Get a Quote
How Does General Liability Insurance Protect Georgia Businesses in Real Life?
Understanding how insurance works in the real world helps clarify its value. Business owners across the state face unexpected events every day, from minor accidents to major lawsuits. To illustrate how these policies function, consider the following realistic claims data for small businesses. This table highlights common scenarios, the average cost of claims without coverage, and how a policy steps in to protect the business owner’s assets.
| Business Type | Claim Scenario | Average Cost Without Insurance | Out-of-Pocket Cost With Insurance |
|---|---|---|---|
| General Contractor | Worker damages client’s main water line, causing severe flooding | $45,000 | Deductible only (e.g., $1,000) |
| Retail Store Owner | Customer slips on a wet floor and fractures their wrist | $35,000 | Deductible only |
| IT Consultant | Accidentally spills coffee on client’s server, destroying data | $15,000 | Deductible only |
| Landscaping Service | Lawnmower kicks up a rock and shatters a neighbor’s window | $2,500 | Deductible only |
As the data shows, even seemingly minor incidents like a shattered window or a spilled drink can result in thousands of dollars in damages. For larger incidents, such as structural water damage or severe bodily injury, the costs can escalate rapidly. When you carry General Liability Insurance, your insurer covers the legal defense costs, medical expenses, and repair bills up to your policy limits. This prevents a single bad day from wiping out your entire business savings or forcing you to liquidate physical assets to pay for a settlement.
How Much Does General Liability Insurance Cost in Georgia?
The cost of securing coverage varies based on your industry, location, payroll, and claims history. High-risk industries like construction generally pay more than low-risk professional services. To help you budget, we have compiled a realistic pricing table showing the average annual premiums for Business Liability Insurance across different common Georgia industries.
| Industry Sector | Risk Profile | Average Monthly Premium | Average Annual Premium |
|---|---|---|---|
| Professional Services (IT, Consulting) | Low Risk | $30 – $45 | $360 – $540 |
| Retail and Wholesale Trades | Medium Risk | $45 – $70 | $540 – $840 |
| Artisans & Contractors (Plumbers, Painters) | High Risk | $70 – $125 | $840 – $1,500 |
| Food & Hospitality (Restaurants, Cafes) | Medium-High Risk | $60 – $110 | $720 – $1,320 |
When insurance companies calculate your specific premium, they evaluate several risk factors. A business with a history of multiple claims will naturally face higher rates than a brand-new business with a clean record. Additionally, your physical location in the state can influence your rate; businesses in densely populated urban areas like Atlanta might pay slightly more due to a higher volume of foot traffic and a statistically higher probability of claims. Fortunately, most small business owners find that the monthly cost of Business Liability Insurance is highly affordable and well worth the peace of mind it provides.
What Are the Limitations of General Liability Insurance?
While General Liability Insurance offers broad protection, it does not cover every risk your business faces. It is crucial to understand the limitations of your policy so you can identify any gaps in your coverage. A standard policy primarily focuses on third-party bodily injury, third-party property damage, and personal or advertising injury. It does not cover injuries to your own employees, damage to your own business property, or professional mistakes.
For example, if one of your employees gets injured on the job, the policy will not pay for their medical bills or lost wages. For that, local law typically requires you to carry workers’ compensation insurance. Similarly, if a fire destroys your inventory or office equipment, this policy will not pay to replace those items; you would need commercial property insurance for that protection. Professional errors, such as giving faulty advice that causes a client financial loss, are also excluded and require professional liability coverage. Understanding these boundaries ensures you do not make the mistake of assuming a single policy covers every possible claim. When shopping for coverage, always review the exclusions list carefully with your agent to ensure your business remains fully protected against all potential liabilities.
Which Other Coverages Work Best With General Liability Insurance?
To build a robust safety net, business owners frequently bundle General Liability Insurance with other specialized commercial policies. Combining coverages ensures that your business assets, employees, and professional reputation remain secure under various circumstances. The table below outlines the most common complementary coverages that local business owners purchase alongside their primary liability policy.
| Complementary Insurance Policy | What It Covers | Why You Need It Alongside General Liability |
|---|---|---|
| Commercial Property Insurance | Your business building, equipment, and physical inventory | Protects your own physical assets from fire, theft, and natural disasters. |
| Workers’ Compensation Insurance | Employee medical bills and lost wages for work-related injuries | Mandatory for businesses with three or more employees. |
| Professional Liability (E&O) | Financial losses caused by professional advice or errors | Protects service providers against claims of negligence or bad advice. |
| Commercial Auto Insurance | Vehicles owned and used by your business for work purposes | Personal auto policies usually exclude coverage for business-use accidents. |
By coordinating these coverages, you can create a protection plan tailored to your specific operations. For instance, many small businesses qualify for a Business Owner’s Policy, which packages general liability and commercial property insurance together at a discounted rate, saving you money while expanding your protection.
What Are the Key Statistics for Georgia Small Businesses?
Georgia is home to over 1.2 million small businesses, representing over 99 percent of all businesses in the state. With so many companies operating, competition is fierce, and the risk of legal disputes is real. According to industry data, slip-and-fall accidents are the leading cause of emergency room visits and represent one of the most common claims filed against Business Liability Insurance policies. The average cost to defend and settle a slip-and-fall claim when a lawsuit is filed can exceed $50,000, a sum that could easily devastate an uninsured small business.
Furthermore, statistics show that nearly 40 percent of small businesses will experience a property or general liability claim within the next ten years. Despite these high odds, a surprising number of small business owners operate without proper coverage, leaving their personal and business assets exposed. In this state, courts do not limit the amount of damages a jury can award for pain and suffering in personal injury lawsuits, meaning a single judgment could far exceed your business’s net worth. Securing a policy is a proactive step that safeguards your hard work and ensures your company remains resilient in a litigious environment.
How Can You Get a General Liability Insurance Quote Today?
Our agency is dedicated to helping local business owners find the right coverage at competitive rates. We understand the unique challenges of operating in Georgia, and we help over 87 customers with general liability coverage in the state every month. Whether you run a small boutique, a bustling restaurant, or a growing construction firm, we can help you tailor a policy that fits your exact needs and budget.
We pride ourselves on providing outstanding customer service, as reflected in our highly rated Google My Business page. Our experienced agents make the insurance process straightforward and stress-free. We can offer you accurate, competitive quotes without any sort of obligation, allowing you to compare options and make an informed decision for your business. Do not leave your livelihood to chance. Contact us today to secure your free quote and take the first step toward protecting your business’s future.
Get in touch with our team!
For questions or concerns, please contact our independent insurance agents by filling out the form!
Blue Ridge Office
95 Progress Circle
Blue Ridge, GA 30513
(706) 632-3400
Ellijay Office
145 Mulberry Street
Ellijay, GA 30540
(706) 635-6000